Debt-to-income ratio calculator.
Find your DTI the way a lender would: monthly debt payments divided by gross monthly income. See which band you are in, how much room you have under the 36% and 43% lines, and what to do about it.
Minimum payments on cards, loan payments, child support or alimony. Not utilities, groceries or insurance.
Still approvable for most loans, including many mortgages, but the extra is thin. Paying down a debt or two would help.
Every debt you clear in Debtless drops this number. The app shows which one to clear first.
Two ratios lenders check.
The front-end ratio is your housing payment alone divided by income. The back-end ratio adds every other debt payment and is the number people usually mean by DTI. Mortgage lenders look at both; car and personal loan lenders mostly look at the back-end figure.
Income is gross, before tax, and can include a co-applicant's. Debts are the monthly payments, not the balances, which is why paying off a small loan with a big payment moves the ratio more than paying down a large balance with a small payment.
Lower it on purpose.
- [ 01 ]
Clear the smallest payment
A $1,500 loan with a $150 payment drops your ratio by the full $150 the month it closes. The snowball calculator finds it. - [ 02 ]
Do not open new credit
A new card's minimum, however small, counts. Wait until after any mortgage or car application. - [ 03 ]
Refinance the expensive one
A lower rate or a longer term cuts the monthly payment, which is what the ratio measures. Use with care; longer terms cost more interest. - [ 04 ]
Raise gross income
Overtime, a raise or documented side income all count. Lenders usually want two years of history for variable income.
Then pay it down.
Ratio in hand, the next step is a payoff order. The snowball calculator clears payments fastest for ratio purposes; the avalanche calculator costs the least. Either way, every debt you finish drops the number.
Keep going.
Smallest balance first. See your payoff order and debt-free date.
Highest interest rate first. The order that costs the least.
What extra principal does to a 30-year loan, in years and dollars.
Pay the car off early and see the interest you skip.
The same plan, kept for you.
Debtless does this math from the payments you log and moves the date every month. Free on iPhone.
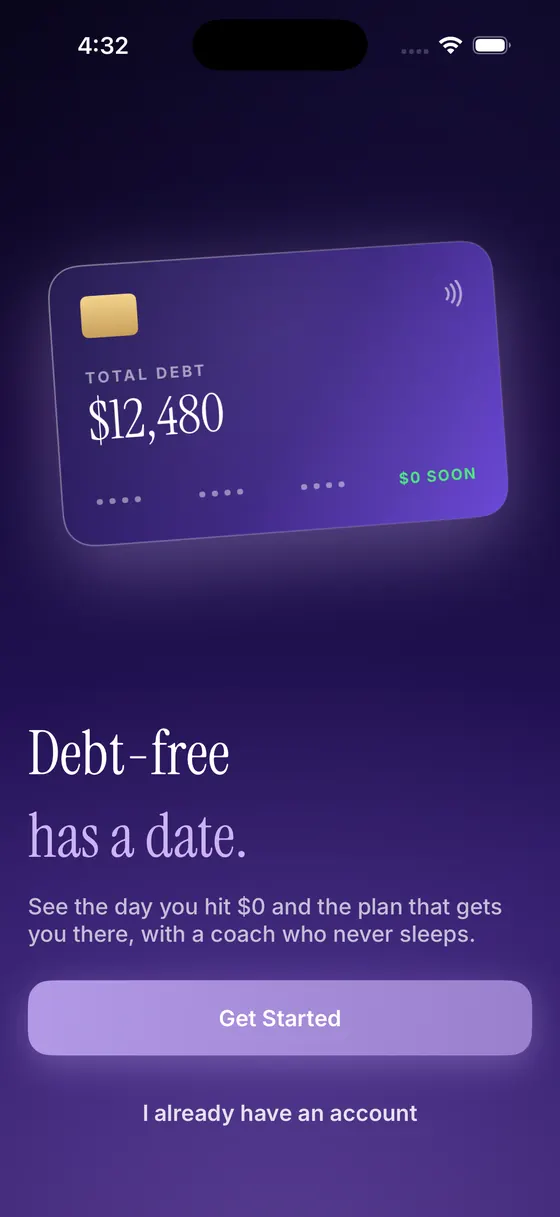
One card, one number, one day you hit zero.
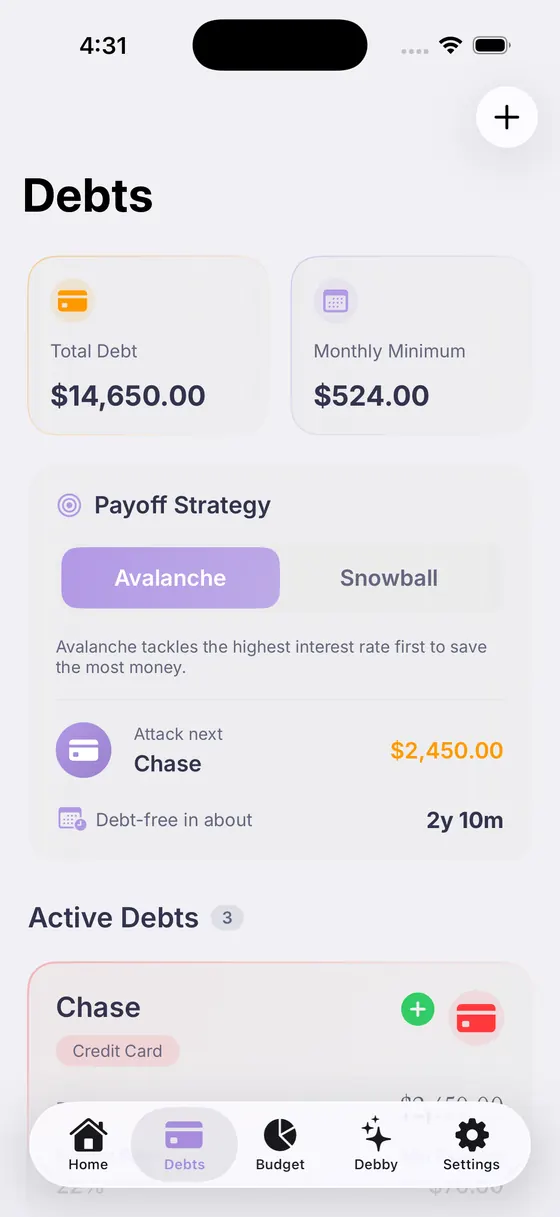
Pick the order, see the date move, switch any time.
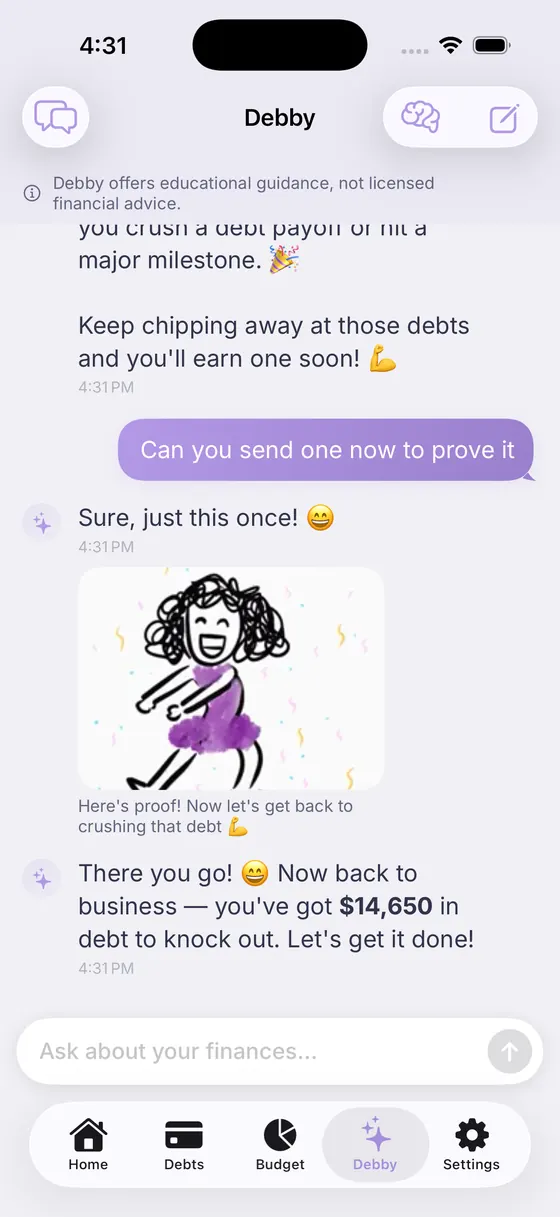
Answers with your real balances, rates and budget.
Questions, answered.
Your debt‑free date is closer than you think.
Add your debts, pick a strategy, and watch the date move.
Free on the App Store