Debt avalanche calculator.
Order your debts by interest rate, from highest to lowest, and see the payoff plan that costs the least. Enter your balances, rates and minimums, then move the extra-payment slider and watch the date change.
On top of every minimum ($525). Your monthly budget: $725
- 01Credit card$6,400 · $1,677 interestmonth 21
- 02Store card$1,200 · $331 interestmonth 23
- 03Car loan$9,800 · $1,106 interestmonth 29
Debtless rebuilds it from your real payments each month and moves your debt-free date as you go. Free on iPhone.
How the avalanche works.
- [ 01 ]
Sort by rate
Highest APR at the top. Balances do not matter for the order, only the price of each dollar you owe. - [ 02 ]
Pay minimums everywhere
Every debt gets its minimum so nothing goes late. Late fees and penalty rates would undo the whole point. - [ 03 ]
Extra to the top
All spare money goes to the highest-rate debt. Each dollar there stops the most interest from accruing. - [ 04 ]
Roll down the list
When the top debt is gone, its full payment moves to the next highest rate. Your monthly budget stays fixed until the last balance is zero.
When the avalanche wins big.
The saving grows with the spread between your rates. A 29% store card next to a 6% auto loan is exactly the situation the avalanche was built for: every month the card sits at the back of the queue costs you four or five times more than the loan does.
When rates are all within a few points of each other the two methods land within weeks of each other. Check your own spread on the comparison page, and if the gap is small, feel free to take the snowball for the early win.
- Interest is charged on the balance you carry, so the biggest saving is always at the top of the list.
- Ask each issuer for a lower rate before you start; one phone call can reorder your list.
- A 0% balance-transfer card can move a debt to the bottom of the avalanche, as long as you clear it before the promo ends.
Take it offline.
The avalanche spreadsheet has this same schedule as formulas for Excel and Google Sheets, so you can keep a copy in your own files.
Keep going.
Smallest balance first. See your payoff order and debt-free date.
Run both orders on your debts and see the difference in dollars and months.
The avalanche version, ordered by interest rate.
How long until zero, and what an extra $50 a month does to the date.
The same plan, kept for you.
Debtless does this math from the payments you log and moves the date every month. Free on iPhone.
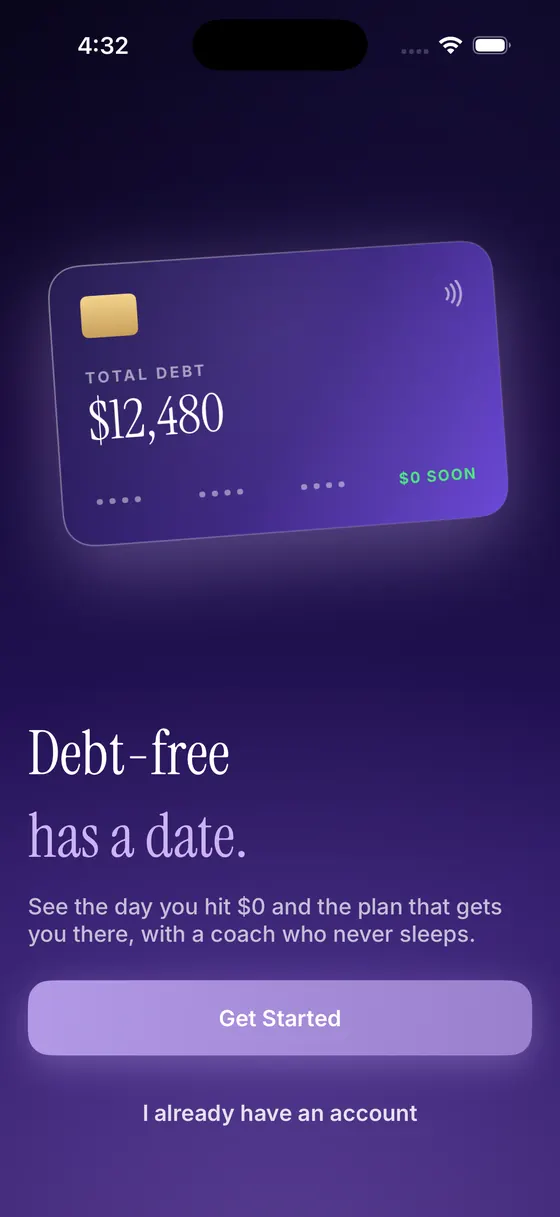
One card, one number, one day you hit zero.
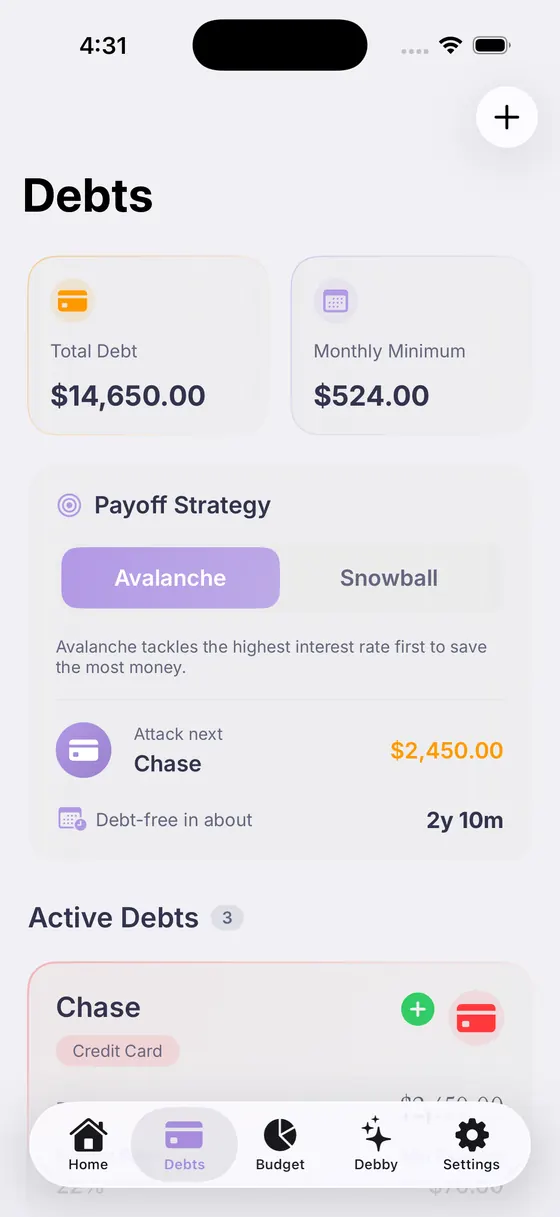
Pick the order, see the date move, switch any time.
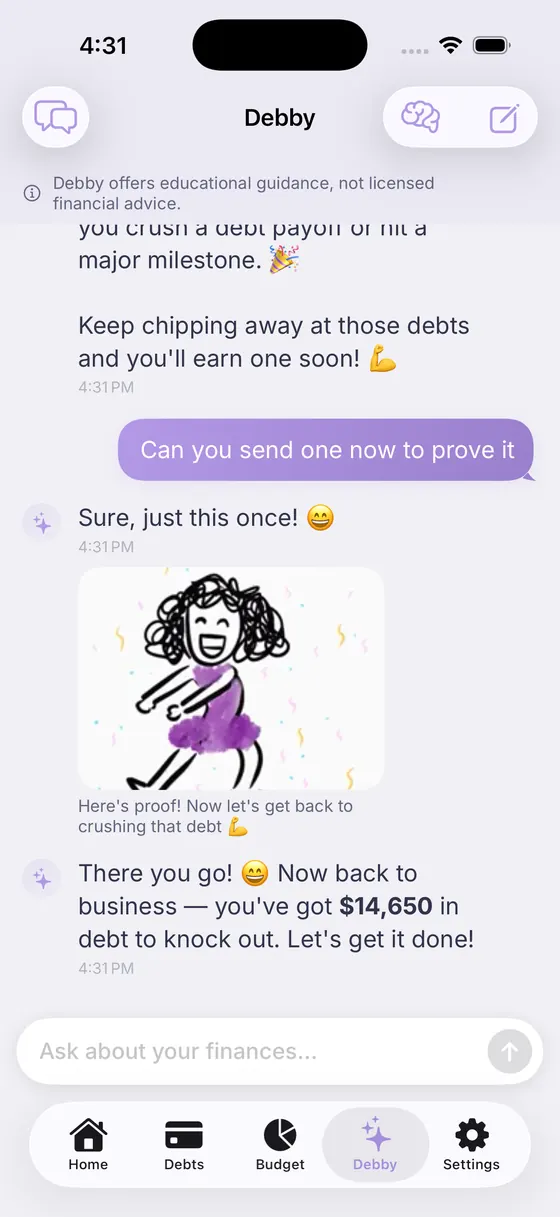
Answers with your real balances, rates and budget.
Questions, answered.
Your debt‑free date is closer than you think.
Add your debts, pick a strategy, and watch the date move.
Free on the App Store