Debt snowball calculator.
Add your debts, set what you can pay each month, and see your payoff order, your debt-free date, and how much interest you avoid compared with paying only the minimums.
On top of every minimum ($525). Your monthly budget: $725
- 01Store card$1,200 · $62 interestmonth 6
- 02Credit card$6,400 · $2,066 interestmonth 23
- 03Car loan$9,800 · $1,110 interestmonth 29
Debtless rebuilds it from your real payments each month and moves your debt-free date as you go. Free on iPhone.
How the snowball works.
- [ 01 ]
List every debt
Balance, interest rate (APR), and the minimum payment. Order them smallest balance to largest. That order is your snowball. - [ 02 ]
Fix your monthly budget
Add up every minimum, then add the extra you can afford. That total is what you pay every month until you are done. It never goes down. - [ 03 ]
Attack the smallest
Minimums on everything else, every spare dollar on the smallest balance. With the example numbers above, the first debt is gone in about six months. - [ 04 ]
Roll it forward
When a debt hits zero, its whole payment moves to the next smallest. The snowball gets bigger with each payoff, which is where the name comes from.
Why people stick with it.
The snowball is not the cheapest order on paper. Paying the highest interest rate first (the avalanche) always costs the same or less. The snowball wins for a different reason: a small debt disappears within months, and that first zero balance is what keeps most people paying extra for the next two years.
The gap between the two methods is often smaller than people expect. Run your own numbers on the snowball vs avalanche page. If the avalanche saves you a few hundred dollars and you trust yourself to stay the course, take it. If the difference is small, take the wins.
- Keep the monthly budget fixed. The rollover is the whole trick.
- Stop adding to the cards you are paying down, or the snowball melts.
- Windfalls (refunds, bonuses) go straight to the current focus debt.
- If one debt has a far higher rate than the rest, consider moving it to the front.
Prefer paper?
Download the free printable snowball worksheet to fill in by hand, or the snowball spreadsheet for Excel and Google Sheets with the same month-by-month schedule as this calculator.
Keep going.
Highest interest rate first. The order that costs the least.
Run both orders on your debts and see the difference in dollars and months.
A one-page PDF to fill in by hand and stick on the fridge.
An honest comparison of the apps people use to get out of debt.
The same plan, kept for you.
Debtless does this math from the payments you log and moves the date every month. Free on iPhone.
One card, one number, one day you hit zero.
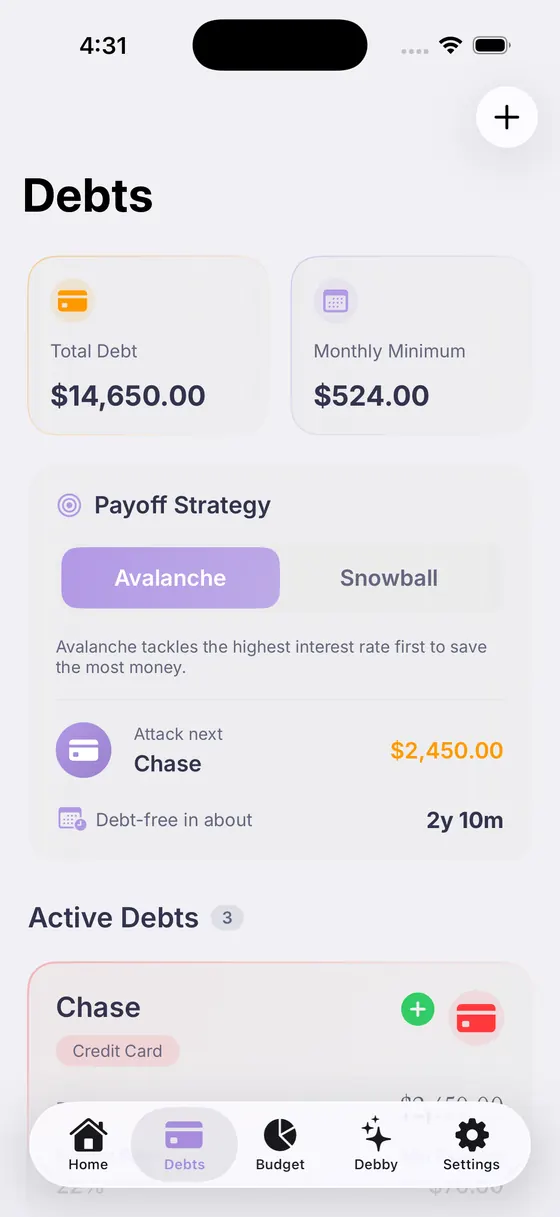
Pick the order, see the date move, switch any time.
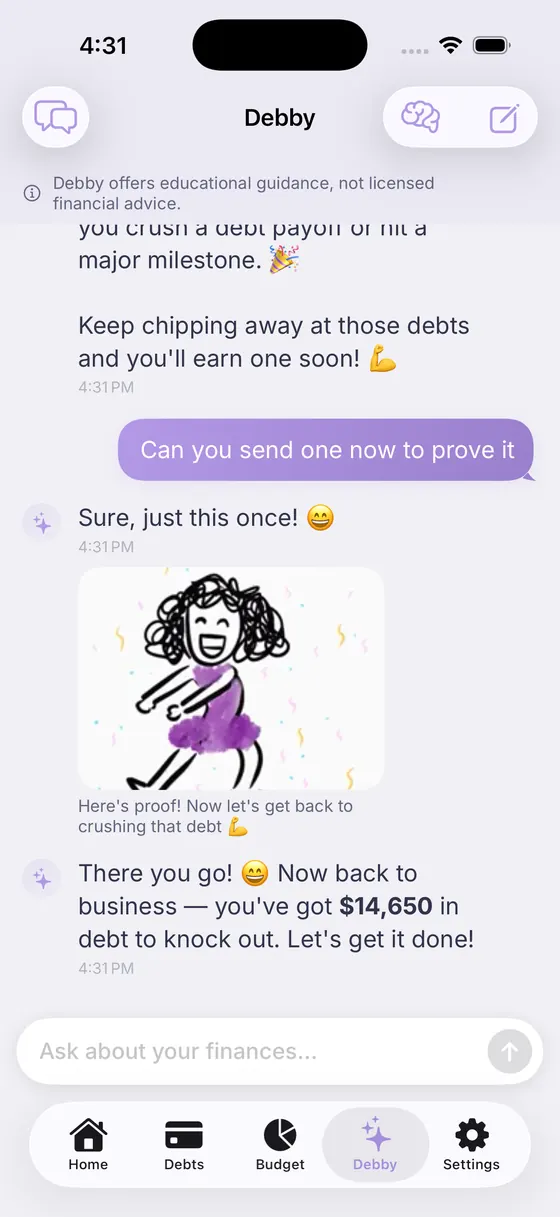
Answers with your real balances, rates and budget.
Questions, answered.
Your debt‑free date is closer than you think.
Add your debts, pick a strategy, and watch the date move.
Free on the App Store