Student loan payoff calculator.
See how early you can pay off a student loan with extra monthly payments or a lump sum, and how much interest that saves against the standard 10-year plan.
Paid on top of the regular payment, straight to principal.
Debtless keeps all your debts on one plan and moves your debt-free date as you pay. Free on iPhone.
Get the most from each extra dollar.
- [ 01 ]
Tell the servicer where it goes
Extra payments should reduce principal, not 'advance' the due date. Most servicers have a setting; some need a note with each payment. - [ 02 ]
Target one loan
Federal loans are usually several loans under one servicer. Send the extra to the highest-rate one, not spread across all. - [ 03 ]
Keep the autopay discount
Most servicers cut the rate by 0.25% for autopay. Set the regular payment to autopay and add the extra manually. - [ 04 ]
Check refinancing carefully
A private refinance can lower the rate but ends federal protections and forgiveness options. Only refinance loans you are sure you will pay in full.
All your loans, one date.
A student loan rarely travels alone. Add it with your cards and car loan in the avalanche calculator to see which to attack first, and check how the payment affects your debt-to-income ratio before any big application.
Keep going.
Any loan: how soon you're done with extra payments or a lump sum.
Highest interest rate first. The order that costs the least.
How long until zero, and what an extra $50 a month does to the date.
Your DTI the way a lender sees it, and how much room you have.
The same plan, kept for you.
Debtless does this math from the payments you log and moves the date every month. Free on iPhone.
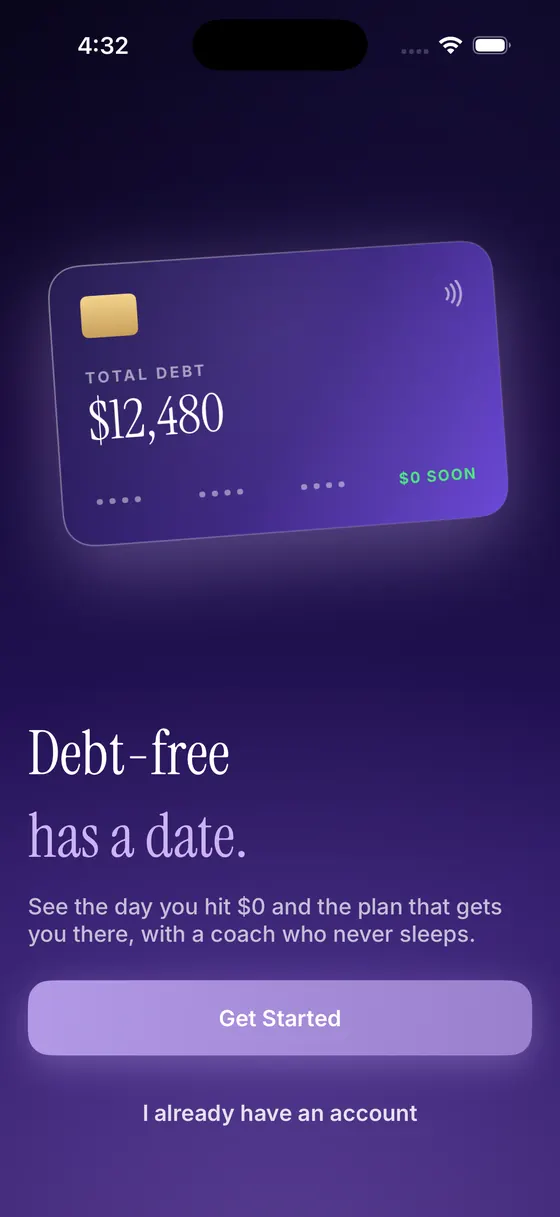
One card, one number, one day you hit zero.
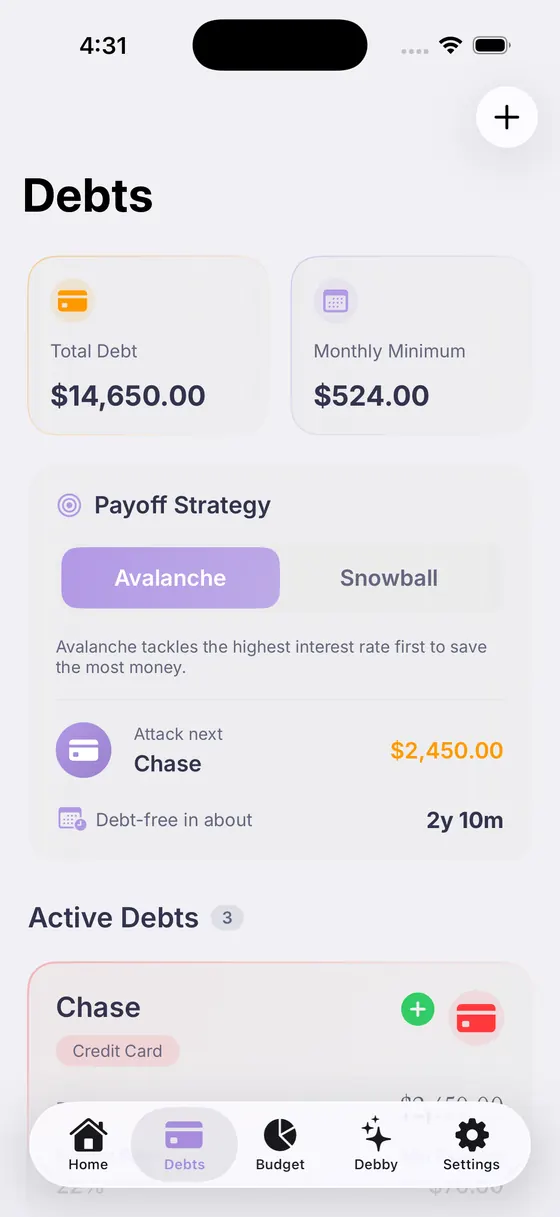
Pick the order, see the date move, switch any time.
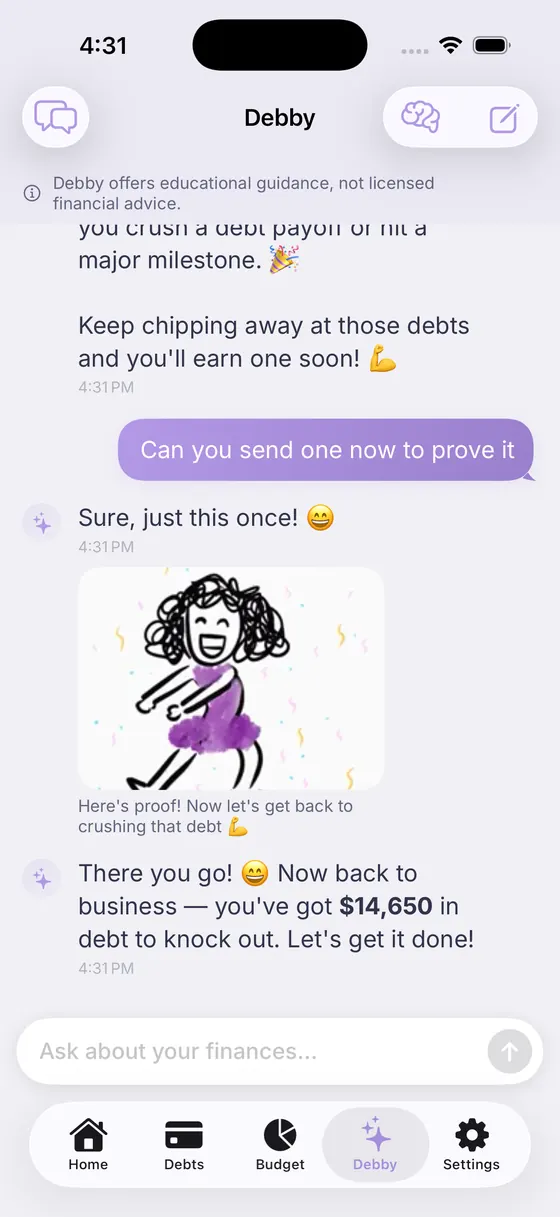
Answers with your real balances, rates and budget.
Questions, answered.
Your debt‑free date is closer than you think.
Add your debts, pick a strategy, and watch the date move.
Free on the App Store